Digital account opening is changing. Is your institution ready?
The way people open financial accounts is changing. What once meant filling out an online form and waiting for a decision is evolving into a connected experience that can verify identity, make decisions in real time, manage risk, fund an account, and move applicants into digital banking, all in one flow.
For credit unions and community banks, this evolution creates a bigger opportunity than simply making account opening more convenient. A faster, more intelligent experience can help institutions compete for deposits, reduce friction, and turn more applicants into new relationships.
And expectations are only getting higher. People are accustomed to digital experiences that are fast, intuitive, and responsive. They expect fewer unnecessary steps, immediate answers, and processes that adapt to their needs rather than forcing everyone through the same path.
Institutions, meanwhile, need to deliver that simplicity without compromising risk management, compliance, or control.
That’s where modern Digital Account Opening comes in: bringing automation, decisioning, verification, and flexibility together to create an experience that’s easier for applicants and more efficient for the institution.
The question isn’t whether people can open an account online. It’s whether your institution is ready for what Digital Account Opening is becoming.
The Digital Account Opening bar is moving.
For most of the last decade, “going digital” meant taking a paper application and turning it into a web form. That was a genuine improvement over requiring a branch visit for everything, and for a while, it was enough to compete.
Applicants filled out fields on a screen instead of a clipboard, uploaded a photo of their ID instead of handing it to a teller, and waited for someone to review what they’d submitted.
The problem is that the process underneath often stayed the same. The form became digital. The workflow didn’t.
Many institutions still rely on manual review queues, batch decisioning, disconnected verification tools, and staff intervention before an account can be opened and funded. The experience may look modern on the surface while the underlying process still operates on older assumptions.
Meanwhile, applicants are opening brokerage accounts, applying for insurance, and using other financial services where decisions happen in minutes rather than days. Their expectations have shifted with every digital experience they use.
A multi-day turnaround on a checking account application, once perfectly reasonable, can now feel like a red flag that an institution hasn’t kept pace.
That’s the shift happening in Digital Account Opening.
It’s no longer enough for an application to be available online. The experience needs to be fast, adaptive, and intelligent, moving applicants from application to account without unnecessary friction.
What changes when Digital Account Opening evolves?
Three gaps often separate a process that simply works from one that performs well, and they tend to appear in a predictable order.
Decisioning speed.
When every application enters a manual review queue, even straightforward ones, the wait has less to do with risk and more to do with staff capacity.
Applicants don’t see that distinction. They simply know they applied and are still waiting.
And every delay creates an opportunity for a faster competitor to win the relationship.
Real-time decisioning changes the equation. Instead of treating every application as a manual task, an intelligent Digital Account Opening workflow can evaluate eligibility as information comes in, automatically move straightforward applications forward, and route exceptions for additional review.
The result isn’t just faster processing. It’s a faster path from applicant to account.
Rigidity.
A single account opening flow can’t account for every applicant or product. A new applicant opening a savings account shouldn’t necessarily follow the same path as an existing account holder adding a joint owner.
A business application may require information that isn’t relevant to a consumer account, while a higher-risk application may need additional review.
Channel fragmentation.
An application started on a phone shouldn’t have to start over on a laptop. An applicant who needs help in a branch shouldn’t have to enter the same information again. And staff shouldn’t have to piece together applications across disconnected systems.
When channels operate separately, everyone feels the friction. Staff deal with duplicated work, manual intervention, and fragmented reporting. Applicants are left wondering why an institution doesn’t know where they are in the process.
A modern Digital Account Opening experience connects those touchpoints through one underlying workflow. Applicants can start online, continue on mobile, or get help from staff without losing their progress.
That continuity isn’t just more convenient. It can reduce abandonment, eliminate unnecessary work, and help more applications make it from start to funded account.
A digital application collects information. Modern Digital Account Opening connects the journey.
Story continued below…
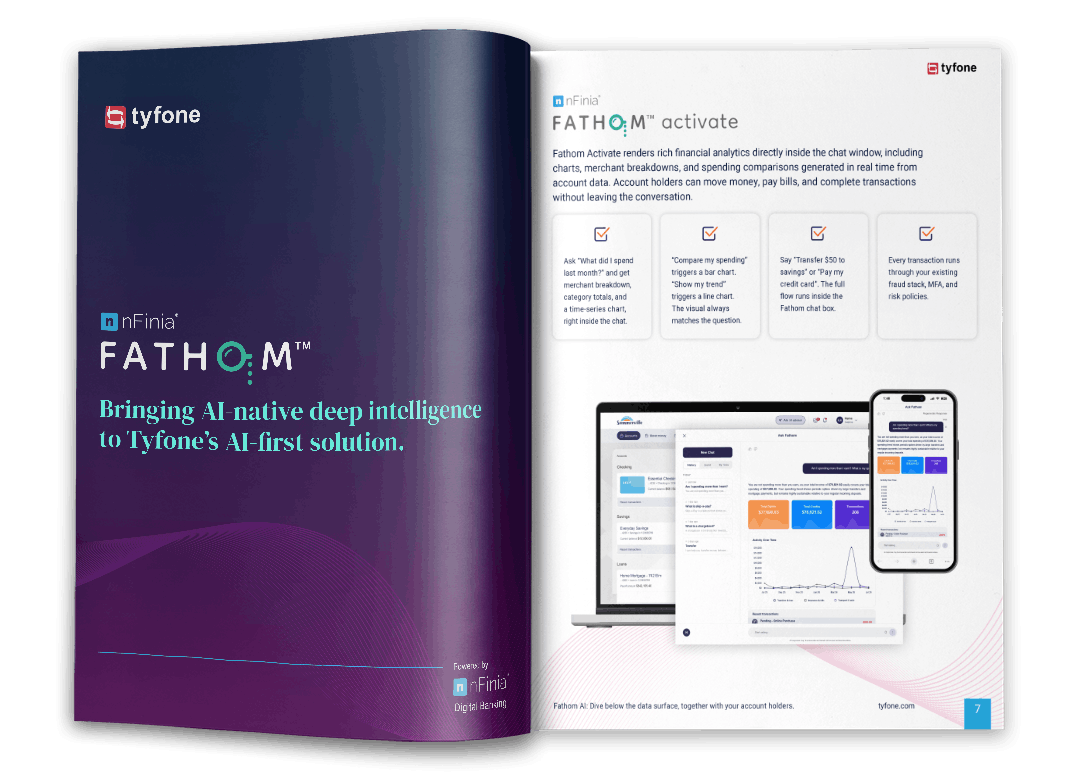
FREE PAMPHLET
Bringing AI-native deep intelligence to Tyfone’s AI-first solution.
Most credit unions and community banks don’t have an AI strategy yet, and account holders aren’t waiting. They’re already comparing every digital experience, banking included, to ChatGPT. Stand still and get left behind.
Fathom is the AI layer woven throughout Tyfone’s digital banking ecosystem, combining account holder financial data, institutional knowledge, and native banking experiences into a single intelligence layer.
What modern Digital Account Opening looks like with Tyfone.
Closing these gaps doesn’t require institutions to start over. It means moving from a rigid application flow to an experience that can adapt to different applicants, products, policies, and risk requirements.
That’s the approach behind Tyfone’s Digital Account Opening, bringing flexibility, real-time decisioning, automated verification, and cross-channel continuity together in one experience.

Flexibility.
No two institutions operate exactly the same way, and their account opening experiences shouldn’t have to either.
Tyfone gives institutions the flexibility to tailor the experience around their products, policies, and requirements without relying on an engineer every time something changes.
Because account opening is never static, institutions can make changes as products, policies, and priorities evolve – without turning every update into a technical project.
Real-time decisioning.
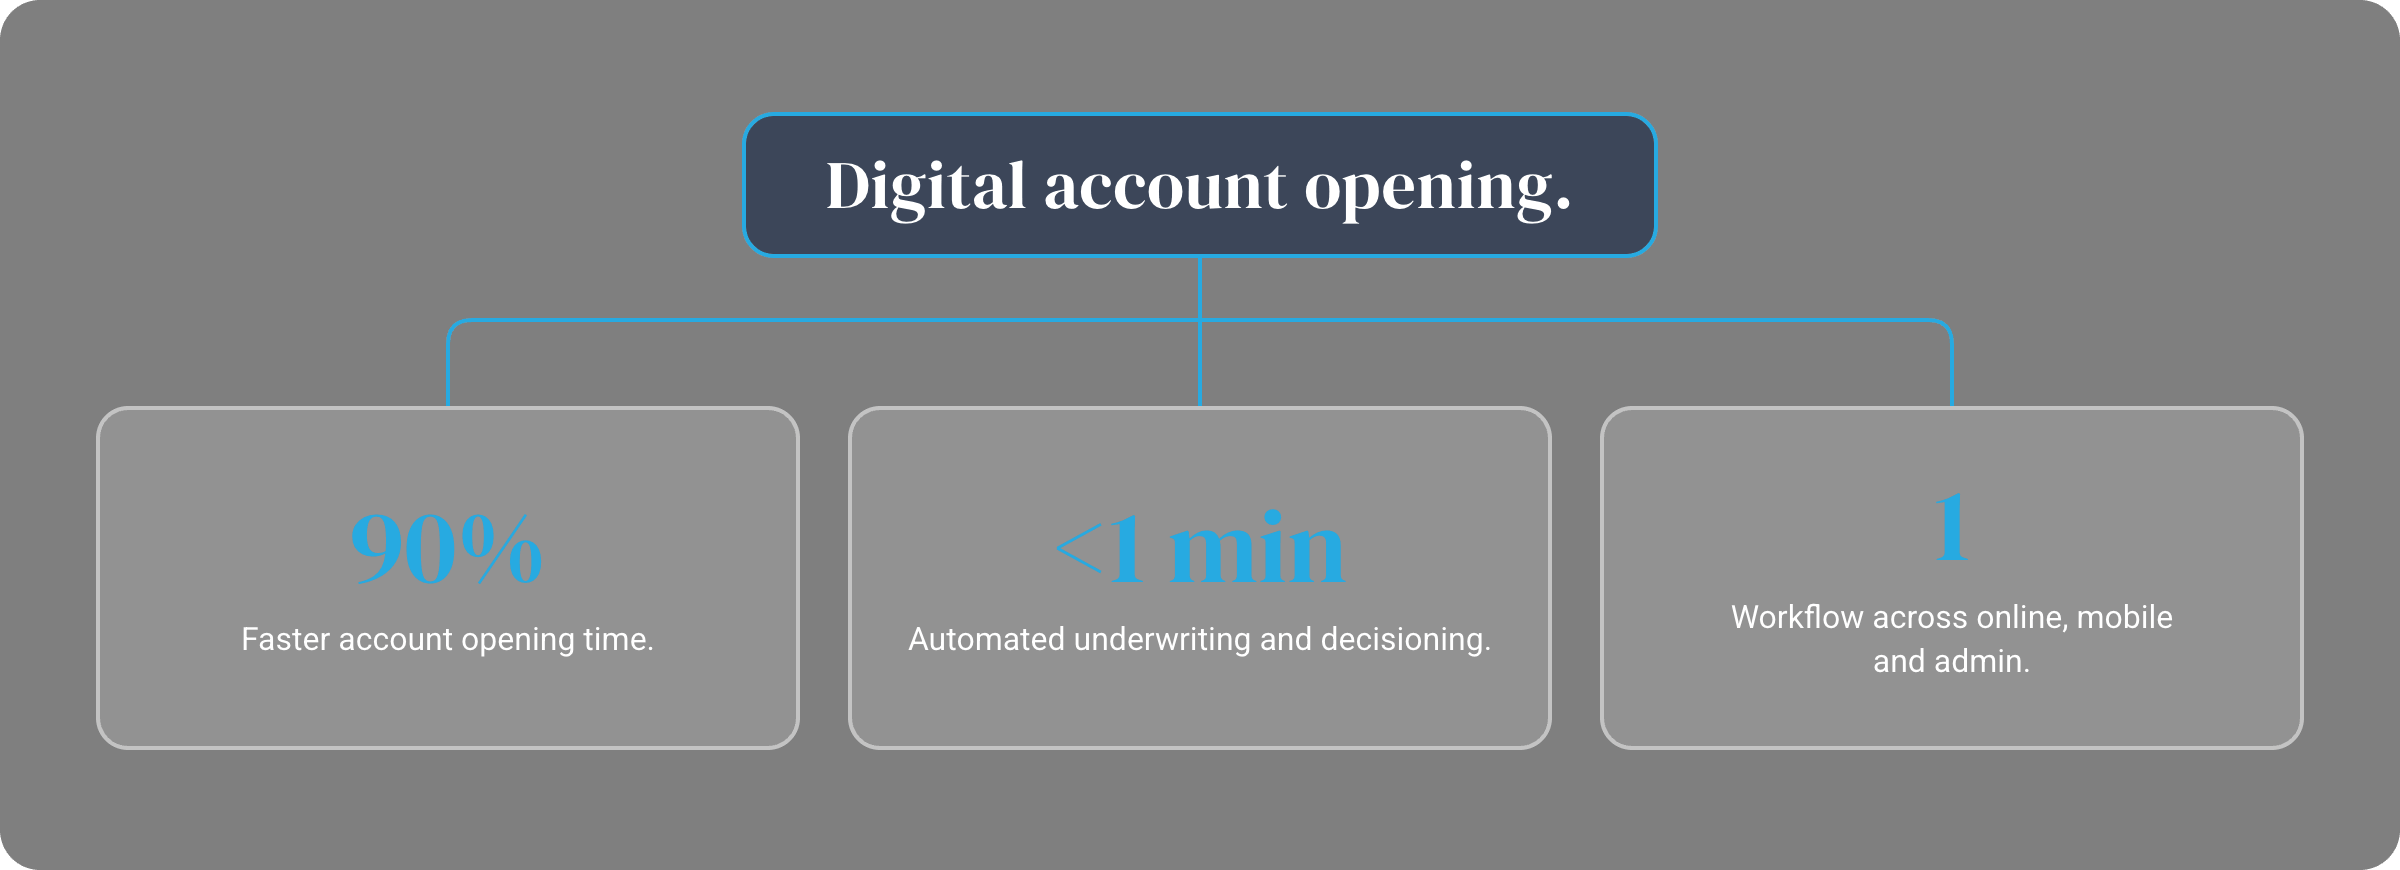
Tyfone’s real-time decisioning engine evaluates eligibility as an application comes in, allowing straightforward applications to move forward without sitting in a review queue.
Institutions using Tyfone’s Digital Account Opening have seen origination time drop by as much as 90%, freeing staff to focus on applications and exceptions that actually require human attention.
Automation where it matters.
Automation doesn’t have to be all or nothing.
Institutions can determine which parts of the process should happen automatically and which should require additional verification or staff review based on their policies and risk appetite.
The result is more automation without giving up control.
Context-aware verification.
Not every applicant needs the same experience.
A new applicant may require more verification than an existing account holder. A primary applicant may follow a different path than a joint owner. And a business application can require information that isn’t relevant to a consumer account.
Tyfone can adjust requirements based on who’s applying, what they’re opening, and what information is already available, reducing unnecessary steps while giving the institution what it needs to make a sound decision.

One workflow, every channel.
Applicants don’t think in terms of channels. They simply expect their progress to follow them.
Tyfone connects online, mobile, in-branch, and staff-assisted account opening through one underlying workflow. Applicants can start on one channel and continue on another without starting over, while staff can step in without recreating information that’s already been provided.
And because the platform is core-agnostic, institutions can bring that experience into their existing technology ecosystem.
Security can’t be the tradeoff.
Speed only matters if it doesn’t come at the expense of security and compliance. That’s the challenge for institutions modernizing Digital Account Opening: creating a faster experience without giving up the controls they need.
Tyfone’s Digital Account Opening runs verification and risk checks throughout the application, helping institutions automate routine checks while maintaining control.
That includes ID and document verification, selfie detection, DMV verification, taxpayer ID validation, sanctions and watchlist screening, PEP checks, adverse media monitoring, and email and phone risk signals.
And it all happens behind the scenes.
Applicants don’t need to know which checks are running or which systems are working in the background. They simply experience a process that keeps moving.
That’s the point.
Good security shouldn’t feel like friction. It should feel like nothing happened at all.
Tyfone puts the complexity behind the experience, helping institutions strengthen risk controls without unnecessarily slowing down straightforward applicants.
Is your institution ready for what’s next?
If your Digital Account Opening experience was built around assumptions that made sense several years ago, it’s worth taking a closer look at how it performs today.
How quickly can you make a decision? How much of the process still depends on manual work? Can the experience adapt to different applicants and products? Can your team make changes without waiting on development? Can applicants move seamlessly between channels? And can you increase automation without compromising risk or compliance?
The answers reveal more than how your current process works. They show whether your Digital Account Opening experience is built for where banking is headed.
Ready to see what’s possible? Schedule a meeting with Tyfone to see Digital Account Opening in action. Or, if you want to explore it on your own, download our free Digital Account Opening pamphlet.