Credit unions see modest growth as membership slips.
Federally insured credit unions posted faster asset and deposit growth in the second quarter, but the median institution continued to lose members.
Federally insured credit unions recorded modest growth in assets, shares and deposits and loans in the year through the second quarter of 2026, even as membership declined at the median, according to the National Credit Union Administration’s quarterly U.S. Map Review.
Assets grew 2.9% at the median over the year ending in June, up from 2.3% during the same period a year earlier. Shares and deposits grew 2.5%, compared with 2.2% a year earlier. Loan growth also turned positive, reaching 0.6% at the median after declining 0.2% in the previous year.
The figures point to uneven conditions across the credit union industry, with growth varying significantly by state and membership trends remaining a challenge for many institutions.
Wyoming and Vermont recorded the fastest median asset growth, at 6.1% and 5.9%, respectively. At the other end of the spectrum, median assets declined 2.2% in Washington, D.C., while they were roughly unchanged in New Jersey.
The pattern was similar for shares and deposits. Wisconsin led the states with median growth of 5.5%, followed by Idaho at 5.4%. Washington, D.C., recorded a median decline of 2.7%, while New Jersey declined 0.8%.
FREE PAMPHLET
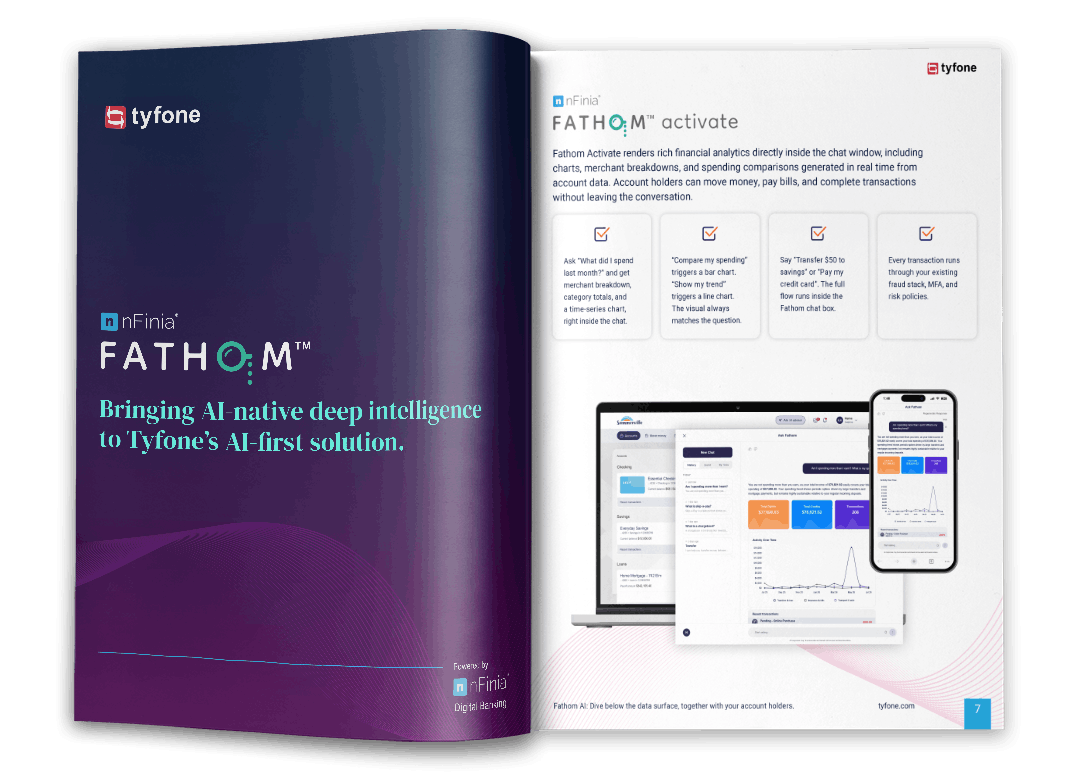
Bringing AI-native deep intelligence to Tyfone’s AI-first solution.
Most credit unions and community banks don’t have an AI strategy yet, and account holders aren’t waiting. They’re already comparing every digital experience, banking included, to ChatGPT. Stand still and get left behind.
Fathom is the AI layer woven throughout Tyfone’s digital banking ecosystem, combining account holder financial data, institutional knowledge, and native banking experiences into a single intelligence layer.
Vermont and Alaska posted the strongest median membership growth, at 4.1% and 2.2%. Membership declined at the median in 34 states, with Arkansas and Nebraska recording the largest declines, at 1.7% and 1.6%.
Loan growth was also uneven geographically. Vermont led with median growth of 6.9%, followed by Florida at 4.8%. Loans declined at the median in Washington, D.C., and 18 states. The review reported a decline of 3.8% in Washington, D.C.; the source material lists Louisiana at “2.6%” without a minus sign.
The NCUA review uses median results, meaning that half of federally insured credit unions recorded a value above or equal to the reported figure and half recorded a value below or equal to it. The annual comparisons measure changes from the end of the second quarter of 2025 through the second quarter of 2026.
Membership was the notable exception to the broader growth in balance-sheet measures. Although total membership continued to increase, membership declined 0.6% at the median, compared with a 0.5% decline a year earlier. About 56% of federally insured credit unions had fewer members than they did a year earlier.
The institutions experiencing membership declines tended to be small. More than half had less than $50 million in assets as of the second quarter, according to the review.
Ken McCarthy is manager of marketing communications at Tyfone, where he monitors the credit union industry and contributes to conversations shaping its future. He previously covered credit unions and community banking for American Banker and S&P Global Market Intelligence. He holds a journalism degree from Point Park University and has more than 15 years of experience covering financial services. He is also the author of three literary fiction novels.