INDUSTRY NEWS
Credit unions face a new digital test: Be invisible.
At a national conference in Philadelphia, industry speakers said members are judging financial institutions against every other digital experience they encounter — while smaller credit unions may still have an advantage that technology cannot easily replicate.
Credit unions are no longer competing only with banks and fintech companies for members’ attention. They are being judged against the last food delivery, ride-share or retail app that made a transaction feel effortless.
That was one of the central themes of a session on member behavior and communication trends at the National Association of State Credit Union Supervisors annual Summit in Philadelphia last month. The speakers, Amanda Tuckey, vice president of marketing and communications for NASCUS, and Dave Shaw, founder of the Austin, Texas, agency Arrow, described a financial-services landscape in which convenience is increasingly expected rather than celebrated.
The standard, they said, is moving toward something harder to see: technology that largely disappears.
Members want interactions without friction, whether they are checking a balance, responding to a fraud alert or moving money. The experience they bring into a credit union branch or app is shaped by everything else they do on a phone.
That raises a difficult question for credit unions, which often cannot match the enormous technology budgets of the largest banks.
The answer is not necessarily to try.
Larger institutions can build increasingly sophisticated digital systems, but smaller credit unions have other ways to distinguish themselves. One is speed to a human being.
The speakers pointed to long phone trees and complicated handoffs as an example of where financial institutions can lose trust. A smaller credit union that can connect a member quickly with an employee may offer something a large institution cannot easily reproduce.
Story continued below…
FREE PAMPHLET
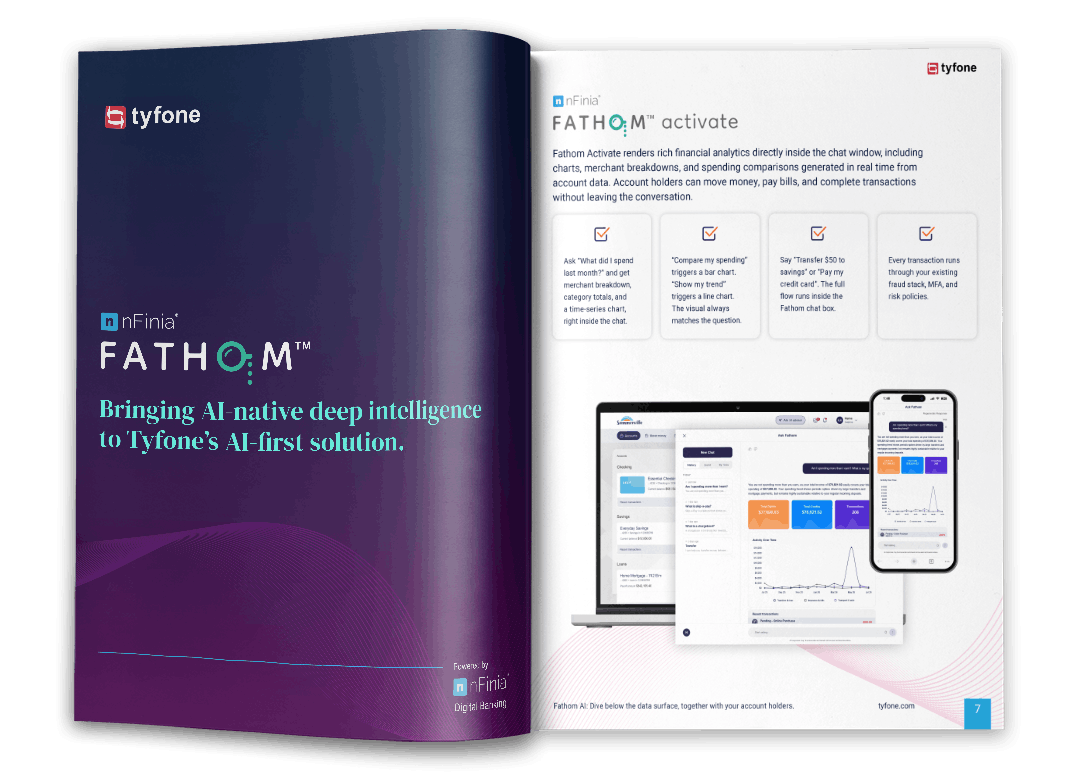
Bringing AI-native deep intelligence to Tyfone’s AI-first solution.
Most credit unions and community banks don’t have an AI strategy yet, and account holders aren’t waiting. They’re already comparing every digital experience, banking included, to ChatGPT. Stand still and get left behind.
Fathom is the AI layer woven throughout Tyfone’s digital banking ecosystem, combining account holder financial data, institutional knowledge, and native banking experiences into a single intelligence layer.
That advantage matters because the digital experience does not exist separately from the physical one.
A member who receives an offer in an app should encounter employees who know how to explain or deliver it. Otherwise, the promise made online collides with reality in the branch. The result is what the speakers described as a disconnect between the digital and real-world experience.
Credit unions can also use partnerships to close some of the technology gap. Rather than trying to build every capability themselves, institutions can examine where they are strong and where a technology or other partner can fill a gap.
That approach is consistent with the cooperative model that has long shaped the industry, the speakers said. The objective is not to outspend the largest technology companies. It is to use available resources more intelligently.
There was another complication: Not every member wants the same kind of experience.
The speakers cautioned against assuming that age alone determines how someone wants to interact with a financial institution. A younger member may prefer to complete everything on a phone, while an older member may want a face-to-face conversation. But age does not always predict financial needs.
A 30-year-old may already have a sophisticated financial relationship with an institution, while a 60-year-old may be buying a first home. Life stage and financial circumstances can matter as much as demographics.
That puts pressure on credit unions to understand what members actually need rather than relying too heavily on broad generational assumptions.
Asking members directly can help. So can examining analytics for points where people encounter friction, the speakers said.
Trust presents another challenge.
Fraud is becoming more sophisticated, including the use of deepfakes and other technologies that can make fraudulent communications appear more convincing. In that environment, consistency across channels can become part of a credit union’s defense.
Members should know how their institution communicates, what it sounds like and where legitimate messages will appear. Employees need to be reinforcing the same expectations in branches, over the phone, in email and through digital channels.
The goal is not simply consistent branding. It is recognition.
That becomes particularly important during moments of stress. A fraud alert arriving late at night, for example, is not a routine interaction. A member who discovers an unauthorized charge needs reassurance and a clear path to help.
The broader lesson from the discussion was that every communication with a member is also a trust-building moment.
That can be easy to overlook when institutions focus on campaigns, products and channels. But the experience is often judged one interaction at a time.
For credit unions, that creates both a challenge and an opportunity. They may not be able to match the technology scale of the largest banks, and the speakers did not suggest that they should. But they can simplify the technology they do deploy, use outside partners where needed and preserve the human accessibility that can set a smaller institution apart.
The competitive question, then, is not simply whether a credit union has the newest technology.
It is whether the technology gets out of the way — and whether, when something goes wrong, a member can still reach someone who will help.
Ken McCarthy is manager of marketing communications at Tyfone, where he monitors the credit union industry and contributes to conversations shaping its future. He previously covered credit unions and community banking for American Banker and S&P Global Market Intelligence. He holds a journalism degree from Point Park University and has more than 15 years of experience covering financial services. He is also the author of three literary fiction novels.